
PEPs Are Gaining Momentum. Is There an Opportunity for You and Your Clients?
In the first few years after being introduced by the SECURE Act of 2019, Pooled Employer Plans (PEPs) were largely viewed as an emerging retirement plan solution. Today, PEPs are becoming a more established option for employers looking to simplify administration, access economies of scale and shift certain responsibilities to experienced professionals.
For retirement plan advisors, that growth represents more than a change in their retirement plan strategy. It creates an opportunity to have a different conversation with clients—one focused not only on investments and plan performance, but also on the growing complexity of running a retirement plan.
The Case for a PEP Is About More Than Scale
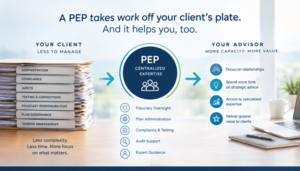
Employers are managing retirement plans in an increasingly complex regulatory environment. Compliance requirements, testing, audits, participant administration, plan governance and fiduciary responsibilities can place significant demands on clients’ internal teams.
For organizations with limited HR or benefits resources, those responsibilities can become a substantial administrative burden.
A PEP can provide a centralized structure designed to streamline many of these responsibilities while giving participating employers access to the infrastructure and expertise of a larger pooled arrangement. That combination is driving interest in PEPs.
But the question for advisors isn’t simply, “Should my client move to a PEP?” A better starting point may be, “Would a PEP address the challenges my client is experiencing today?”
Look for the Signs of a PEP Opportunity
Every client and retirement plan is different, but certain circumstances may indicate that it is time to explore whether a pooled structure, such as a PEP, could make sense.
Administrative complexity is becoming a burden
If a client’s HR or benefits team is spending significant time managing retirement plan administration, correcting plan-related issues and coordinating multiple service providers, there may be an opportunity to centralize responsibilities under a PEP.
Fiduciary responsibilities are creating concern
Plan sponsors remain accountable for their fiduciary obligations, even when they outsource certain functions. A PEP can provide a structure in which certain fiduciary and administrative responsibilities are assumed by designated providers. For advisors, this can create an opportunity to help clients better understand which responsibilities they retain—and which can be delegated.
The plan has become increasingly difficult to manage
Growth can be a good thing for a retirement plan, but it can also introduce complexity. More participants, more assets, additional compliance requirements and evolving plan needs can stretch internal resources.
In general, PEPs provide access to infrastructure and expertise that would otherwise be difficult for an individual employer to maintain.
Your Client Wants to Focus on Their Business—Not Plan Administration
For many employers, the goal isn’t necessarily to take less responsibility for their retirement plan. It’s to spend less time on administrative tasks that aren’t central to their business. A PEP can allow an employer to remain engaged in the plan while relying on experienced retirement plan professionals for designated administrative and fiduciary functions.
One Size Doesn’t Fit Every Employer
PEPs can offer meaningful advantages, but they aren’t necessarily appropriate for every employer or every situation. Plan design is one important consideration.
A client may have specific eligibility provisions, matching or nonelective contribution requirements, vesting provisions or other features that need to be evaluated against the PEP’s available design.
Some employers may also have unique circumstances that make a single-employer structure more appropriate. That’s why the conversation should begin with the client’s needs and whether or not a PEP is even something to consider.
What is creating the most administrative friction? What responsibilities does the sponsor want to retain? What would it like to delegate? And what does the client need its retirement plan to accomplish? Those questions can help determine whether a PEP deserves a closer look.
Where Advisors Can Add Value
PEPs can create an opportunity for advisors to become even more valuable to their clients. Advisors can help employers:
Identify the opportunity
Recognize when administrative complexity, fiduciary concerns or limited internal resources suggest that joining a PEP should be considered.
Evaluate the fit
Compare the client’s current structure, plan design and objectives against what a PEP can provide.
Navigate the transition
Help coordinate the many moving pieces involved in transitioning from an existing plan to a PEP.
Stay focused on the bigger picture
Continue advising on the areas where the advisor’s expertise matters most, while designated administrative and fiduciary responsibilities are handled by the appropriate professionals. This is an area where the right PEP partner can make a difference.
The Right PEP Partner Can Extend Your Capabilities
For advisors, the value of a PEP isn’t simply the pooled structure itself. It is also the expertise, infrastructure and fiduciary framework behind it.
An experienced PEP provider, known as the Pooled Plan Provider (PPP), can help take on designated responsibilities, provide centralized administration and support the operational requirements of the pooled arrangement—while complementing the advisor relationship rather than replacing it.
That creates a different kind of opportunity for advisors.
Instead of viewing PEPs as a risk to the traditional advisor relationship, consider how they can help you address clients’ growing administrative and fiduciary needs while allowing you to remain focused on the relationship, advice and strategic guidance you provide.
Is a PEP Right for Your Client?
PEPs are gaining momentum because they address several challenges employers are facing today: administrative complexity, limited resources, fiduciary concerns and the desire to access greater scale. For advisors, that can be the starting point for a valuable client conversation.
When a client’s retirement plan becomes more complex, the answer isn’t always to do more. Sometimes, it’s to rethink who is doing what.
Pentegra can help advisors evaluate PEP opportunities, navigate the transition and provide experienced fiduciary and administrative support—helping you deliver more value without giving up the client relationship.
Ready to explore whether a PEP could be a fit for one of your clients? Talk with a Pentegra expert today. Contact us at solutions@pentegra.com or 855- 549-6689.